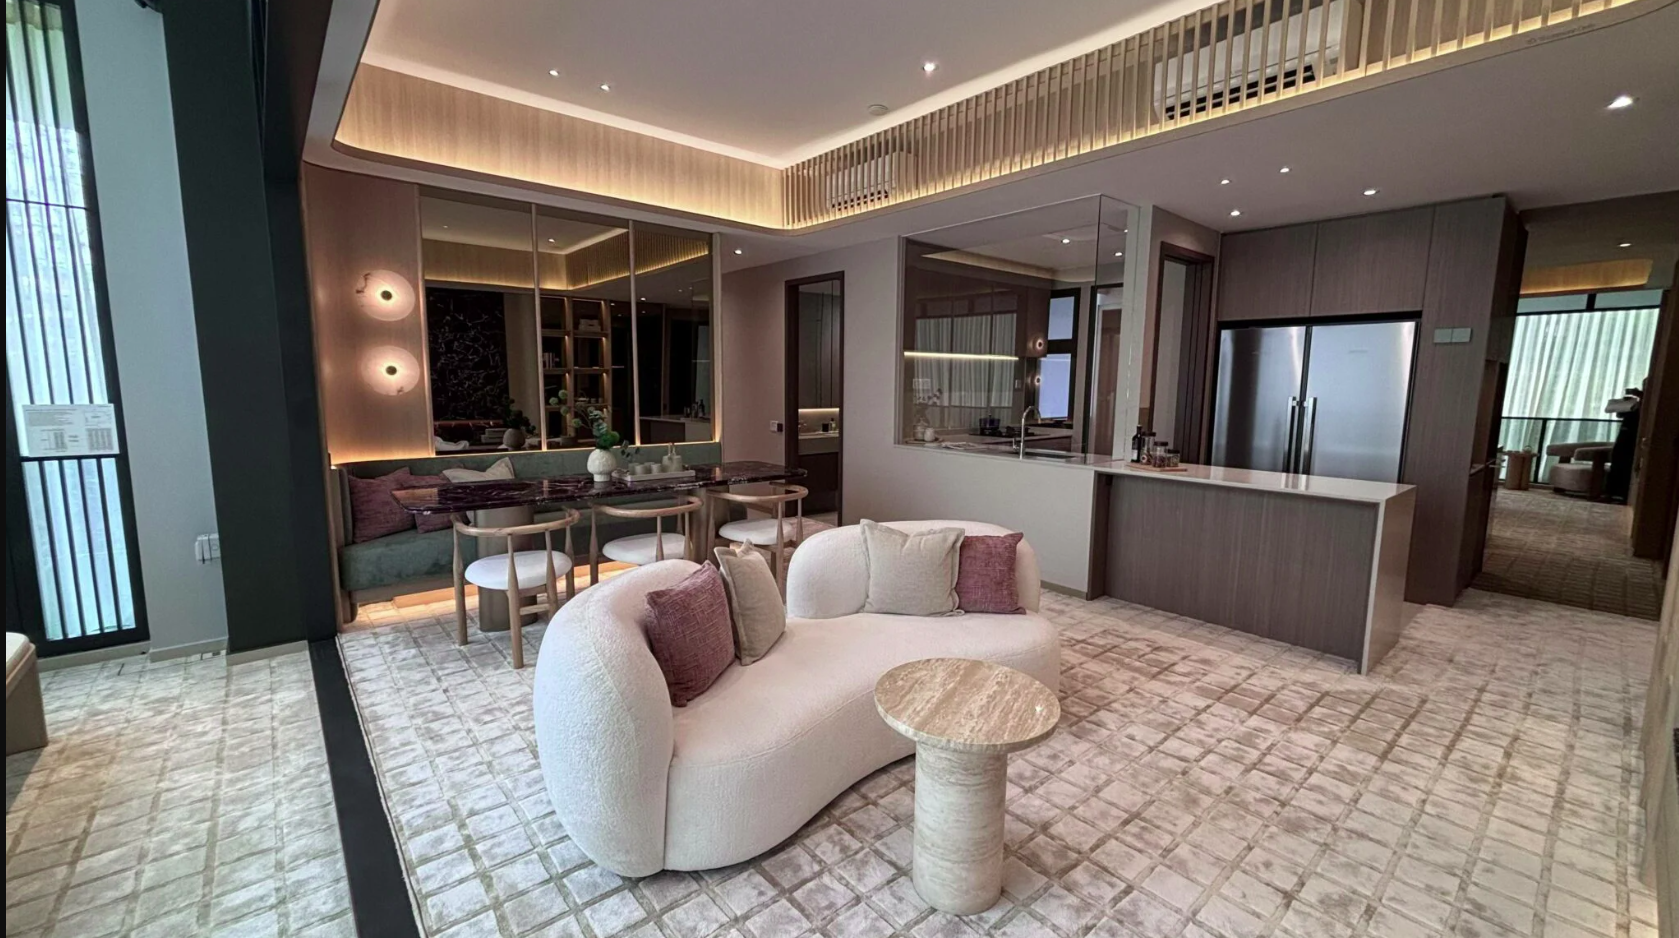
New private home sales nearly double in September, buyers remain selective
Singapore developers sold 296 new private homes, excluding executive condominiums (ECs), in September 2026, up 93.5 per cent from August and 16.1 per cent higher than a year earlier. However, the rebound came after a relatively quiet month, with buyers continuing to favour projects offering more competitive pricing as the market heads into a busier launch period.
According to data released by the Urban Redevelopment Authority (URA) on Oct 15, September's sales rose from 153 units in August to 296 units. The Lunar Seventh Month, which ended on Sept 10, had weighed on sales activity in August, while developers also held back new launches during the period.
Despite the monthly recovery, developers sold just 1,180 new private homes in the third quarter of 2026, excluding ECs. This was the lowest quarterly total since the third quarter of 2024, when 1,160 units were sold.
Of the 296 new private homes sold in September, most came from projects that had already launched. Developers introduced 158 new units for sale during the month, comprising 70 units at Amberwood at Holland, 65 landed homes at Luxus Hills, and 23 strata-landed homes at Belgravia Ace.
Amberwood at Holland was the only new condominium launch in September. The 212-unit development in District 10 sold 24 of the 70 units released in its first phase, translating to a take-up rate of about 34 per cent. Its median transacted price was $3,021 psf.
More than 60 per cent of Amberwood's units sold were four- and five-bedroom apartments, while around two-thirds of the transactions exceeded $3 million. Its larger layouts and low-density residential setting may appeal to families, although the higher purchase quantum remains an important consideration.
The stronger sales performances in September came from projects already on the market. Terra Hill and The Sen, both in the Rest of Central Region (RCR), were among the best-selling developments, recording median prices of $2,209 psf and $2,386 psf respectively.
Terra Hill's September sales were its highest monthly total since its launch in February 2023, when it sold 89 units. Based on lodged caveats, the 270-unit development was about 92 per cent sold by the end of September. Its median transacted price was also the lowest monthly figure recorded since launch, suggesting that price adjustments on the remaining units helped attract buyers.
Luqman Hakim, Chief Data & Analytics Officer at 99.co, said: "Nevertheless, previously launched developments such as Terra Hill and The Sen continued to attract buyers, recording 32 and 25 transactions respectively. This suggests that underlying demand remains resilient, although buyers are increasingly discerning in their purchasing decisions."
Both Terra Hill and The Sen transacted below the September median price of $2,522 psf for new non-landed private homes in the RCR. Their performances highlight how existing projects can continue to compete for demand when their pricing compares favourably with the wider market.
The continued sales at projects such as Lentor Gardens Residences, Dunearn House and Union Square Residences also indicate that buyer interest can extend beyond the initial launch period. In particular, more attractive pricing has helped Union Square Residences reduce its unsold inventory.
The Rest of Central Region led September's new private home sales, with 131 units transacted, up from 72 units in August. The region accounted for 44.3 per cent of all new private homes sold during the month.
The Outside Central Region (OCR) followed closely, with 125 units sold, compared with 57 units in August. Together, the RCR and OCR accounted for 256 units, or 86.5 per cent of total new private home sales excluding ECs.
Meanwhile, sales in the Core Central Region (CCR) rose from 24 units in August to 40 units in September. The CCR accounted for the remaining 13.5 per cent of transactions, with Amberwood at Holland contributing 24 sales.
The stronger showing in the RCR and OCR suggests that demand remained concentrated in city-fringe and suburban developments. However, the September figures also reflect project-specific factors, including price adjustments at existing developments and the availability of larger homes.
In the OCR, Lentor Gardens Residences was the best-selling project, with 22 units sold at a median price of $2,348 psf. The development was among several projects launched earlier in the year that continued to attract buyers after their initial sales periods.
The CCR's relatively smaller sales volume does not necessarily indicate an absence of demand for prime homes. September's results included several higher-value transactions, particularly at developments offering larger apartments and landed properties. However, the higher purchase quantum of these homes means that their potential buyer pool is generally more limited.
September also saw an unusually high number of landed home transactions. Developers sold 19 landed properties during the month, the highest monthly volume since April 2018, according to Huttons Asia.
The transactions included 18 terrace houses at Luxus Hills and nine semi-detached strata-landed units at Belgravia Ace. These homes contributed to the higher purchase quantum of properties sold in the OCR, where the median transaction value reached $3.2 million.
The preference for larger homes reflects a segment of demand that is less focused on the lowest possible entry price. Some households may be willing to pay more for additional space, while the relatively limited supply of new landed homes may also be attracting buyers who would otherwise consider resale properties.
At the higher end of the market, the priciest new private residential transaction in September was a 2,088 sq ft apartment at Skywaters Residences, which sold to a Singaporean for $11.48 million. It was the only new condominium unit to transact for at least $10 million during the month.
Two 2,056 sq ft apartments at Upperhouse at Orchard Boulevard also changed hands for $7.8 million and $7.3 million respectively.
These transactions show that demand for higher-value homes remains present, although they should not be taken as evidence of a broad-based acceleration in the luxury market. The overall volume of new private home sales remained modest, and the month's results were influenced by the mix of homes available and sold.
The EC market recorded 23 new sales in September, up 27.8 per cent from 18 units in August. Coastal Cabana continued to lead the segment for the fourth consecutive month, selling 19 units at a median price of $1,811 psf.
Rivelle Tampines accounted for two of the remaining transactions, while Altura and Otto Place each recorded one sale.
The relatively low volume comes amid limited new supply. No new EC project has launched since Rivelle Tampines in March 2026, and URA figures showed that only 145 units remained unsold across launched EC projects at the end of September.
The limited inventory could support sales at existing developments, although the pace of transactions will also depend on the availability of suitable units and buyers' affordability. With fewer new EC launches entering the market, purchasers have a narrower range of projects to consider in the near term.
[[nid:746233]]
The outlook for new private home sales is likely to improve in the final quarter of 2026, with several major projects scheduled to launch. These include Lucerne Grand, The Serra Residences, and Thomson Reserve, which, together with other upcoming developments, will provide a more substantial pipeline of new homes.
Lucerne Grand in Jurong provided an encouraging start to October, selling more than 61 per cent of its 570 units during its launch weekend on Oct 3 and 4. The result suggests that buyers remain willing to commit to new developments when the location, pricing and product offering align with their expectations.
The Serra Residences, a freehold development on Bassein Road in District 11, is scheduled to launch on 16 October. Its freehold tenure may appeal to buyers who place a premium on ownership tenure, although its pricing and unit mix will also influence demand.
Meanwhile, Thomson Reserve, a 1,268-unit development along Bright Hill Drive, is scheduled to launch on 31 October. It is expected to be the largest new private residential project to enter the market this year, giving buyers a wider selection of units and layouts in the Upper Thomson area.
[[nid:746674]]
The wider supply pipeline remains relatively limited compared with last year. Developers launched an estimated 4,790 private residential units in the first nine months of 2026, down 41.9 per cent from 8,247 units during the same period in 2025. New private home sales over the same period totalled around 5,334 units, a year-on-year decline of 30.4 per cent.
The lower volumes should be viewed in the context of a quieter launch calendar. Several Government Land Sales sites awarded in earlier periods are expected to contribute new projects only in 2027, which could influence the supply of launches available to buyers over the next year.
September's rebound offers some encouragement for the private residential market, but the underlying figures suggest a recovery that remains selective. The month-on-month increase came off a low base, while the third-quarter sales tally was the lowest in two years.
The performance of Terra Hill and The Sen also shows that pricing can influence demand even after a project has been on the market for some time. Meanwhile, Amberwood at Holland's more measured take-up highlights the challenges of selling larger, higher-quantum homes to a narrower pool of purchasers.
Luqman said: "While September's rebound in developer sales is encouraging, overall transaction volumes remain relatively modest, suggesting that buyers continue to adopt a cautious and selective approach amid interest rate uncertainty and broader macroeconomic concerns."
He added that new launches are likely to remain a key driver of developer sales, with market activity sensitive to interest rate developments and wider economic conditions.
[[nid:746477]]
……Other

One-stop lifestyle app dedicated to making life in Singapore a breeze!


 English
 简体中文
Comments
Leave a comment in Nestia App