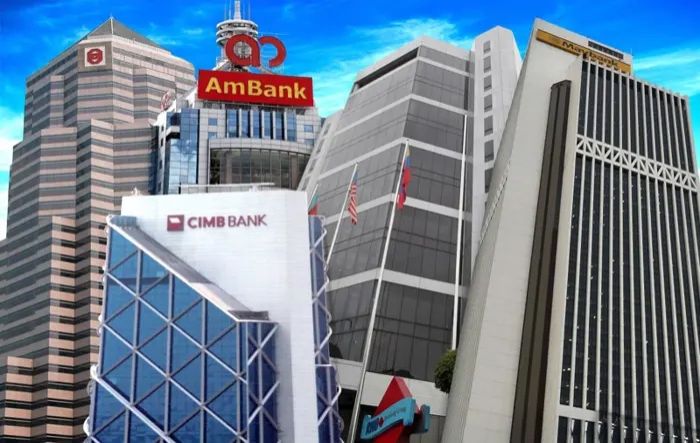
Stable fundamentals, reforms bolster banking industry
MALAYSIA’S banking sector is well positioned for sustained growth, driven by favourable domestic economic fundamentals and strategic structural reforms.
Household financing and credit services are projected to remain firmly supported by stable labour market conditions, steady income growth and ongoing policy support.
A key catalyst for personal financial services is the implementation of phase two of the salary adjustment under the Public Service Remuneration System, which is expected to bolster household disposable income and debt-servicing capacity.
Overall household credit risk is anticipated to stay stable and manageable.
To safeguard financial stability and encourage responsible borrowing, Bank Negara Malaysia and the government are introducing enhanced pre-emptive credit risk management measures.
Effective Jan 1, 2027, consumers applying for new personal financing exceeding RM100,000 must complete a financial education module delivered by the Credit Counselling and Debt Management Agency. Financial service providers will also enforce stricter debt service ratio limits and net disposable income thresholds tailored to individual borrower profiles.
Up to end-July 2026, the Malaysian banking system displayed high resilience and strong capacity to absorb potential shocks while sustaining uninterrupted credit flows to households and businesses underpinned by strong capital buffers and sufficient liquidity.
Capital ratios are well above regulatory minimums. As at end-July 2026, the common equity tier-one capital ratio stood at 14.6%, the tier-one capital ratio at 15.1%, and the total capital ratio reached 18.2%.
Liquidity remained ample, with an aggregate liquidity coverage ratio of 148.7% and a net stable funding ratio of 114.8%. The system’s loan-to-fund ratio held steady at 82.8%, supported by deposit growth which comprised 73.2% of total funding.
Credit risk remained well-contained, marked by a low gross impaired loans ratio of 1.4% as at end-July 2026.
Banks maintained conservative provisioning practices, keeping the loan loss coverage ratio (including regulatory reserves) at 125%. Household impaired loans stayed particularly low at 1.1%, backed by a median debt service ratio of 32.1%.
Total outstanding loans expanded by 5.6% year-on-year to RM2.44 trillion as at end-July 2026.
Total loan applications grew 10% to RM975.7bil while approvals surged 14.7% to RM517.4bil.
Loan disbursements increased 4.3% to RM1.3 trillion and repayments rose 3.6% to RM1.29 trillion.
Business financing expanded strongly by 8% to RM837.4bil propelled by a 19.2% jump in loan applications (RM441bil) and a 29.8% surge in approvals (RM275.1bil), led by working capital needs and notable disbursements in the electrical and electronics and information and communication technology sectors. Household loans grew 5.1% to RM1.45 trillion, anchored by residential property purchases and passenger car financing.
……Read full article on The Star Online - Business
Entertainment Malaysia

One-stop lifestyle app dedicated to making life in Singapore a breeze!


 English
 简体中文
Comments
Leave a comment in Nestia App