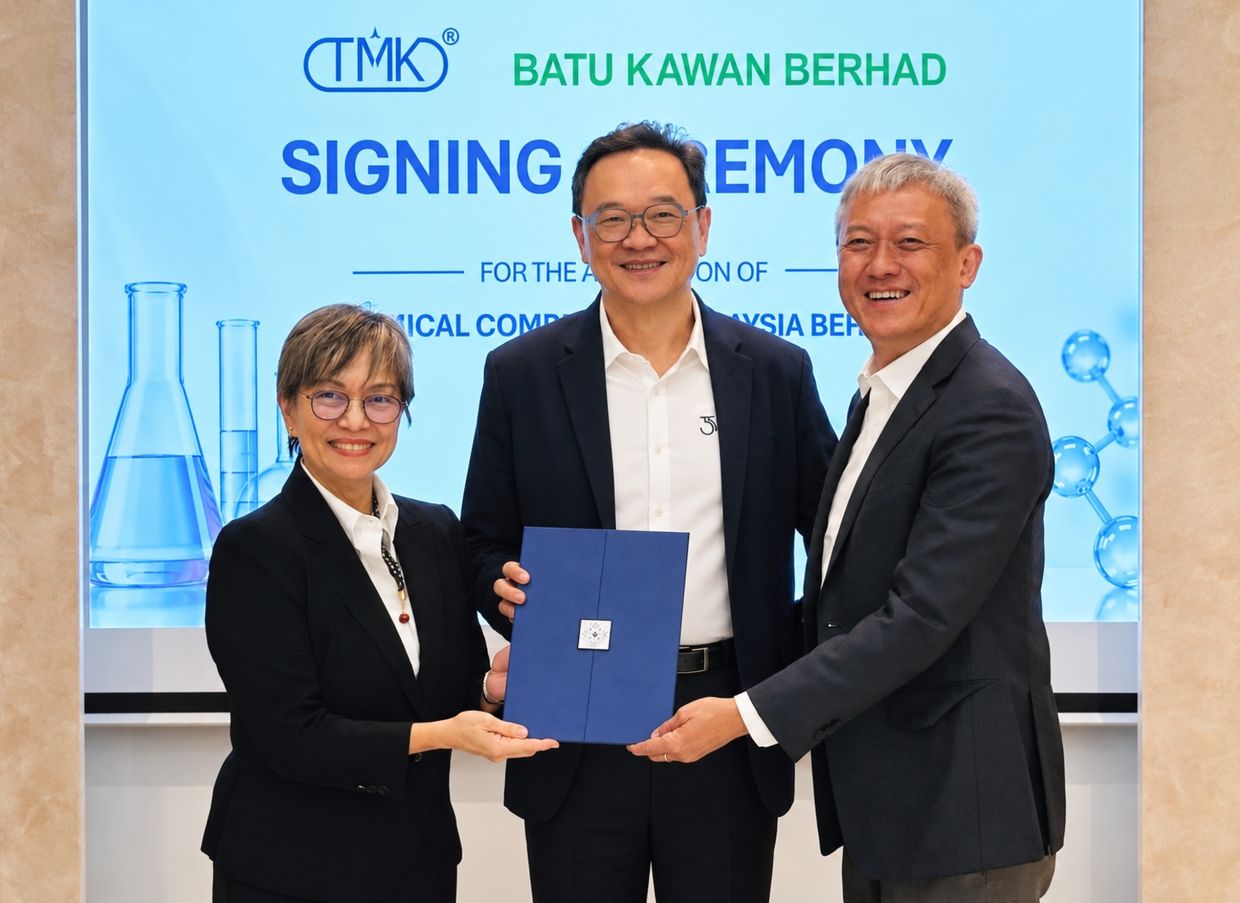
TMK Chemical to acquire CCM for RM939.9mil
KUALA LUMPUR: TMK Chemical Bhd
has entered into a conditional agreement to acquire Chemical Company of Malaysia Bhd (CCM) for RM939.9mil.
In a statement, TMK said the purchase consideration will be satisfied through RM438.5mil in cash and the issuance of 262.5 million new TMK shares at RM1.9098 each.
CCM is Malaysia’s largest chlor-alkali producer and a leading manufacturer and supplier of chlor-alkali chemicals, sulphur derivatives and polymer chemicals. It operates nine facilities across Peninsular Malaysia.
Its products serve industries including rare earth processing, water treatment, rubber gloves, oleochemicals, oil and petrochemicals, electronics and textiles.
For the financial year ended Sept 30, 2025, the CCM group recorded revenue of RM701.8mil and profit after tax and minority interest of RM76.6mil.
TMK said the acquisition would combine its chemical trading, storage and logistics operations with CCM’s manufacturing base and broader product range.
The enlarged group is expected to benefit from more efficient procurement, logistics and distribution, improved asset utilisation and greater economies of scale.
TMK executive director and managing director Wong Kin Wah said the acquisition marked a significant step in the group’s transformation strategy, noting that CCM had grown substantially since its privatisation and delisting in 2021.
He said Batu Kawan had since consolidated its chemical operations under CCM, expanding the company’s manufacturing base and product portfolio.
“With close to four decades of experience in the inorganic chemicals industry, TMK understands this business well and sees a strong strategic fit between CCM’s capabilities and what we have built over the years.
“The combination will allow us to create a stronger, more integrated chemicals business with significantly greater scale and reach,” Wong said.
Separately, RHB Research initiated coverage of TMK with a “buy” recommendation and a target price of RM3.60, implying a potential upside of 19% and an estimated FY2026 dividend yield of about 3%.
RHB said TMK offered exposure to Lynas Rare Earths Ltd’s expansion in Malaysia, while the CCM acquisition would reinforce its position as the country’s leading chlor-alkali supplier.
According to RHB, Lynas has increased its chemical consumption by between 60% and 70% since early 2026, contributing to tighter hydrochloric acid supply. Hydrochloric acid prices have more than doubled year to date.
The higher chemical prices have benefited TMK’s profitability, with its gross profit margin rising to 26% in the second quarter of 2026 from 19% a year earlier.
RHB estimated that CCM generated an average annual profit after tax of RM75mil to RM80mil over the past three years. It also projected that the acquisition could provide TMK with an additional RM165mil to RM185mil in annual hydrochloric acid revenue.
The research house forecast TMK’s earnings to grow 57% in FY2026, supported by higher selling prices and sales volume. Earnings are projected to rise by a further 13% in FY2027 and 14% in FY2028, aided by the completion of the group’s second Banting plant.
RHB valued TMK at 20 times projected FY2027 earnings, in line with the Kuala Lumpur Production Index’s average valuation, citing the group’s earnings growth and improving margins.
The research house said delays to Lynas’ expansion, chemical production overcapacity in Malaysia and weaker-than-expected industrial activity as key downside risks.
Subject to the relevant approvals, the CCM acquisition is expected to be completed by the first quarter of 2027. The transaction excludes certain CCM assets and interests specified in TMK’s announcement dated Sept 18, 2026.
……Read full article on The Star Online - Business
Entertainment Malaysia

One-stop lifestyle app dedicated to making life in Singapore a breeze!


 English
 简体中文
Comments
Leave a comment in Nestia App