The Quiet 2027 Interest Rate Hike: Why Bank Negara’s “Steady Hand” Is Your Final Window To Prepare
Subscribe to our FREE Newsletter, or Telegram and WhatsApp channels for the latest stories and updates.
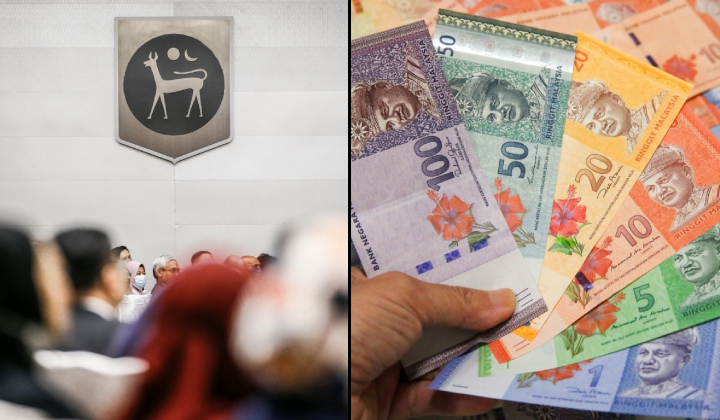
Bank Negara Malaysia (BNM) closed out its final Monetary Policy Committee (MPC) meeting of 2026 by keeping the Overnight Policy Rate (OPR)—the country’s benchmark interest rate that dictates all other borrowing costs—steady at 2.75%.
While mainstream headlines are celebrating this as a sign of manageable inflation and stable borrowing costs to end the year, the financial metrics behind the scenes tell a different story.
This isn’t a permanent pause—it is a strategic calm before a looming normalisation cycle.
While BNM’s official statement sounds calming, the banking world is already acting like a rate hike is a done deal.
Behind the scenes, the wholesale interest rate that Malaysian banks charge each other to borrow money (known as the Kuala Lumpur Interbank Offered Rate or KLIBOR) has quietly climbed to 3.56%.
Because this is significantly higher than BNM’s current 2.75% rate, it clearly signals that financial markets are already bracing for a sharp interest rate increase early next year.
For everyday Malaysians, a rate hike isn’t just an abstract macroeconomic data point.
It hits floating-rate retail loans—where the Standardised Base Rate (SBR) moves in tandem with the OPR—immediately.
Major research houses, including OCBC, ANZ, HSBC, and CIMB, are forecasting a 25-basis-point hike to 3.00% as early as the 21 January or March 2027 MPC meetings.
If you are servicing a RM500,000, 30-year home loan at a baseline 4.00% interest rate, here is exactly what that 0.25% shift does to your cash flow:
The Silent Principal Trap: If you choose to keep your monthly instalment unchanged to avoid the immediate cash crunch, the bank doesn’t let you off the hook. The compounding interest will eat into your principal repayment, quietly stretching your loan tenure by two additional years.
The Immediate Payment Hit: Your monthly instalment will automatically increase by RM72.62, pulling an extra RM871.44 from your household budget annually for the same asset.
With consumer price pressures expected to edge higher in 2027 due to Budget 2027 subsidy rationalisations and volatile global commodity lines, the next few months represent a final defensive window for your personal finances.
For Homeowners: Call your financing institution now to evaluate your current Debt Service Ratio (DSR) or explore whether locking into a fixed-rate package can shield you from upcoming rate hikes.
For Cash Savers: Do not tie up liquid capital in long-term, 12-to-24-month fixed deposits right now. Keep your funds flexible in short-term holdings so you can capitalise on the high-yield promotional FD campaigns banks will roll out to compete for liquidity once the OPR hits 3.00%.
The current 2.75% rate is a gift of predictability.
Use it to fortify your cash buffers before the central bank forces your hand in the first quarter of next year.
READ MORE: OPR Made Easy: What It Is And How It Affects Your Wallet
This article is for informational and educational purposes only and does not constitute formal financial advice. Borrowing profiles and banking terms vary widely; readers should consult a licensed financial advisor or their respective lending institutions before making personal financial decisions.
Share your thoughts with us via TRP’s Facebook, X, Instagram, or Threads.
……Read full article on The Rakyat Post - News
Other

One-stop lifestyle app dedicated to making life in Singapore a breeze!


 English
 简体中文
Comments
Leave a comment in Nestia App